
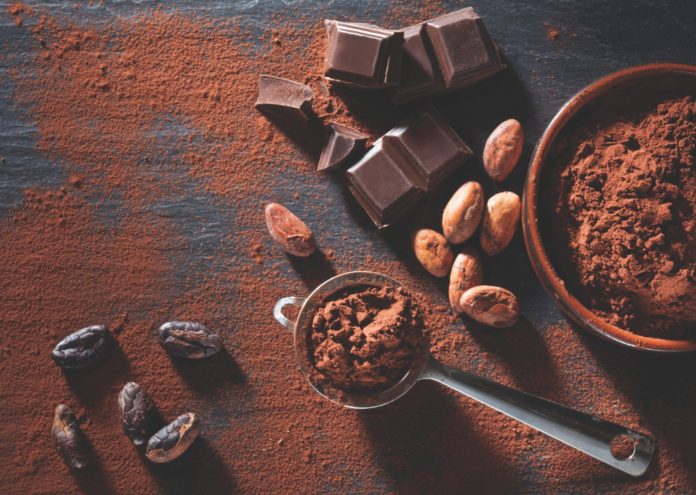
As cocoa costs reshape chocolate manufacturing, brands are rethinking formulations, pricing and product strategies to balance consumer expectations with profitability.
Cocoa has become the chocolate industry’s scarcest certainty. Prices have come off their December 2024 peak, but the crop underneath them remains fragile, concentrated and slow to rebuild. Manufacturers have drawn the conclusion that matters; rather than wait for cocoa to become cheap and plentiful again, they are learning to make chocolate that needs less of it. Recipes are being re-balanced, cocoa butter and cocoa solids are being partly replaced, and some of the world’s largest brands are now funding research into chocolate-like products made with little or no cocoa at all, across both mass and premium ranges.
For India, a roughly `40,000 crore chocolate and confectionery market that imports most of its cocoa, this shift will shape what goes into the `5 bar, how premium chocolate justifies its price, and how chocolate competes with the rest of the confectionery shelf.
A Crop Under Strain
For much of the 2010s, cocoa prices remained broadly within a US$2,500-3,000 per tonne range. That relative stability began to unravel as production weakened across the world’s principal cocoa-growing regions. Global cocoa production was close to 5.0 million tonnes in the 2022/23 season. It fell to approximately 4.4 million tonnes in 2023/24, a decline of ~12% in a single season as adverse weather, crop disease, ageing trees and longstanding underinvestment affected production across key West African origins. The significance of that decline was amplified by concentration. Côte d’Ivoire and Ghana, the world’s two largest cocoa-producing countries, together accounted for approximately 49% of global production in 2024/25.
This concentration means that weather, disease or structural production challenges across a relatively small part of West Africa can materially alter the global cocoa balance. The 2023/24 season demonstrated precisely that. Global production declined sharply, the market moved into a sizeable deficit and inventories tightened. Prices reflected that vulnerability: from around US $3000 per tonne on average in 2023, cocoa climbed to approximately US $12,900 per tonne at its December 2024 peak.
Production has since recovered partially, reaching around 4.7-4.8 million tonnes in 2024/25, while exceptionally high cocoa prices also moderated processing demand. By September 2026, cocoa prices had fallen to approximately US$5,600 per tonne, more than 50% below their peak.
Yet this is not quite a return to the pre-crisis environment.
Cocoa remains substantially more expensive than before the disruption, while the underlying geographic concentration of production has not materially changed. More importantly, the industry has experienced how rapidly an agricultural supply shock can move through inventories, procurement costs, manufacturing margins and eventually consumer prices.
Against this backdrop, three shifts are becoming visible across sourcing, product architecture and ingredient innovation.
Cocoa Sourcing is Becoming More Diversified
The first visible response has been a widening of the cocoa sourcing base.
For decades, the economics of cocoa naturally favoured established producing regions. Scale, processing infrastructure, farmer networks and established trading systems reinforced West Africa’s position at the centre of global supply. Côte d’Ivoire and Ghana alone accounted for approximately 49% of global cocoa production in 2024/25, making the industry particularly exposed to production disruptions across these two origins. The 2023/24 shock brought the vulnerability on the other side of that concentration into sharper focus.
Large manufacturers are already expanding sourcing relationships beyond their traditional supply base. Nestlé, for example, has increased cocoa procurement from Brazil while working with local farmers on practices aimed at improving productivity and strengthening supply resilience. Latin American producing markets are also gaining relevance within the broader supply mix, with Ecuador expanding production and Brazil seeking to rebuild its position as a larger cocoa producer.
The shift does not represent an exit from West Africa. Côte d’Ivoire and Ghana retain production scale, farmer networks and cocoa infrastructure that cannot be replicated quickly elsewhere. Rather, established West African supply is increasingly being complemented by additional origins, deeper farmer relationships and upstream productivity programmes.
The change is subtle but strategically important. The objective of sourcing is increasingly not simply to secure cocoa efficiently, but to secure it reliably, giving greater weight to diversified origins, longer-term farmer relationships, productivity programmes and investment further upstream in the agricultural value chain.
The Quiet Reformulation: Less Cocoa in Every Bite
The second shift is visible in the product itself.
The conventional response to commodity inflation follows a familiar sequence: absorb part of the increase, improve productivity, raise prices and, where necessary, adjust grammage. Cocoa’s recent price movement has brought another variable into play: the amount of cocoa-intensive chocolate contained within the product itself.
Manufacturers are addressing this through both formulation and format. In the UK, Nestlé and Pladis have changed formulations across selected products, with reductions in cocoa butter content also affecting how certain products can be described under local chocolate-labelling requirements.
Portfolio development is moving in parallel. Filled bars, coated wafers, bites, chocolate-covered nuts and products combining chocolate with caramel, biscuit, nougat, fruit and other centres allow manufacturers to deliver a chocolate-led proposition without relying on the same cocoa intensity as a solid tablet.
The economics differ meaningfully by format. A plain chocolate tablet remains inherently more exposed to cocoa costs, while a filled or coated product distributes ingredient cost across chocolate and non-chocolate components. Format and formulation are therefore increasingly working alongside price and grammage as mechanisms through which manufacturers manage cocoa exposure.
At the premium end, however, the relationship is different. High-cacao, single-origin and craft products deliberately retain cocoa intensity because cacao quality and provenance form part of the proposition itself. Here, the consumer is paying not simply for indulgence but also for origin, processing, flavour characteristics and craftsmanship.
The emerging portfolio response is therefore not a uniform reduction in cocoa. Instead, cocoa is playing a more differentiated role across the portfolio, lower intensity where indulgence can be delivered through fillings, texture and format, and greater emphasis on cocoa itself where quality and provenance support premium positioning.
From Cost-Cutting to R&D: The Alternative Chocolate Pipeline
The third response sits further out on the innovation curve.
Cocoa-butter equivalents (CBEs) and compound coatings are not new. Specialty fats from shea, sal, illipe and mango kernel have long been used where regulations allow. What is new is the scale and ambition of investment in ingredients that recreate the chocolate experience with far less cocoa butter and cocoa solids, or none at all. That work is increasingly being led by the largest brands and processors, not by start-ups at the edge of the category.
Three broad technology routes are now visible:
- Cocoa-free chocolate from other crops. Planet A Foods’ ChoViva, made by fermenting and roasting ingredients such as sunflower seeds and oats, is the most commercially advanced. Barry Callebaut signed a long-term partnership in 2025 to scale it globally; Mars used it in a Balisto product in early 2026; and Nestlé launched it in Choco Crossies Snack Vibes in March 2026, describing it as a way to future-proof confectionery portfolios against supply disruption. Cargill’s NextCoa, based on roasted grape and sunflower seeds, is working in the same space.
- Cocoa butter alternatives. Suppliers such as Bunge, with its shea-based Coberine range, are improving fats that behave like cocoa butter in melt, snap and gloss, which allows manufacturers to reduce the most expensive fraction of the cocoa bean.
- Cell-cultured cocoa. Mondelēz-backed Celleste Bio showed milk chocolate prototypes made with cultivated cocoa butter in April 2026. Lindt & Sprüngli invested in Food Brewer, which grows cocoa cells in bioreactors, and Barry Callebaut is researching cell-cultured cocoa with the Zurich University of Applied Sciences.
Before the recent cocoa shock, investment in alternatives was driven largely by sustainability considerations, including land use, climate exposure and agricultural impact. The commodity crisis has added a further rationale: supply-chain optionality. Alternative fats, cocoa extenders, cocoa-free ingredients and new production technologies are increasingly being explored not only for their sustainability potential, but also for the flexibility they can provide against volatility in the cost and availability of conventional cocoa.
India: Growth Across Two Different Chocolate Economies
The global cocoa shock reaches India from a different starting point. While the country has a large and growing chocolate market, its domestic cocoa base remains relatively small. Cocoa production has increased from around 19,000 tonnes in 2017 to an estimated 28,000-30,000 tonnes in 2024, concentrated largely in southern India. Even at this level, domestic production meets less than a fifth of India’s cocoa requirement and accounts for less than 1% of global output. Indian chocolate manufacturers therefore remain closely exposed to movements in international cocoa supply and prices.
That exposure is becoming more significant as chocolate itself takes a larger role within India’s confectionery market. The combined chocolate and confectionery market has grown from approximately `29,000 crore in FY 2020 to an estimated `40,000 crore in FY 2026 and is projected to reach approximately `56,000 crore by FY 2031, growing at CAGR of 7% for the next five-year period. Chocolate accounted for ~ 61% of the market by value and balance accounted by the confectionary segment.
But underneath that growth are two very different chocolate economies, and cocoa inflation affects each differently.
At the mass end, affordability remains embedded in the category architecture. Across Indian packaged foods, `5 and `10 packs together account for more than half of volumes, while the `20 price point has been gaining importance. Chocolate operates within the same low-unit-price environment, where familiar absolute price points play an important role in driving trial, frequency and reach. Large manufacturers have therefore continued to protect key entry price points even through periods of elevated input costs, using a combination of grammage, pack architecture, pricing and operating efficiencies to manage the economics behind them.
This makes cocoa inflation particularly consequential at the mass end. Moving a `100 product to `110 represents a 10% increase; moving a `5 product to `6 represents a 20% increase and, more importantly, breaks an established consumer price point. The ability to pass commodity inflation directly to the consumer is therefore constrained precisely where volumes and distribution are widest.
At the premium end, the economics work differently. Cocoa can become part of what creates the premium rather than simply an input whose cost needs to be managed. Fabelle has built its proposition around luxury chocolate, gifting and differentiated formats, while Manam has made Indian cacao provenance, farmer relationships and farm-to-bar production central to its proposition. Cadbury Studio Creations represents another expression of the same premiumisation through differentiated flavours, formats and gifting.
The route to market is also beginning to diverge. Digital channels have become increasingly relevant for premium chocolate, where higher realisations and lower volumes can support a different distribution model and help address some of the challenges associated with physical reach and temperature-controlled handling. Mass confectionery, by contrast, continues to derive its scale predominantly through general trade and broad physical availability.
This distinction also changes the competitive boundary of chocolate. At low price points, chocolate competes not only with other chocolate brands but with a wider basket of affordable indulgence. Hard-boiled candy, toffees and other sugar confectionery participate in many of the same impulse occasions without carrying the same direct exposure to cocoa. As chocolate prices increased, this difference became more visible, with consumers in parts of the market shifting towards smaller packs and lower-priced confectionery alternatives. Premiumisation therefore does not always require a materially higher ticket; it can also take the form of greater product sophistication within an existing affordability threshold.
Beyond the Price Cycle
Taken together, these shifts suggest that the impact of the cocoa shock will outlast the price spike that triggered it. Globally, manufacturers are becoming more deliberate about where they source cocoa, how much of it different products require and where alternatives can provide greater flexibility. In India, the same pressure is playing out against a market where affordability remains critical at one end even as cacao quality and provenance create value at the other. As the market continues to grow, the challenge is therefore no longer simply managing the price of cocoa but determining where cocoa is central to the consumer proposition and where product architecture can reduce dependence on it. Cocoa prices may continue to move through cycles; the industry’s approach to its most important ingredient has already begun to change.